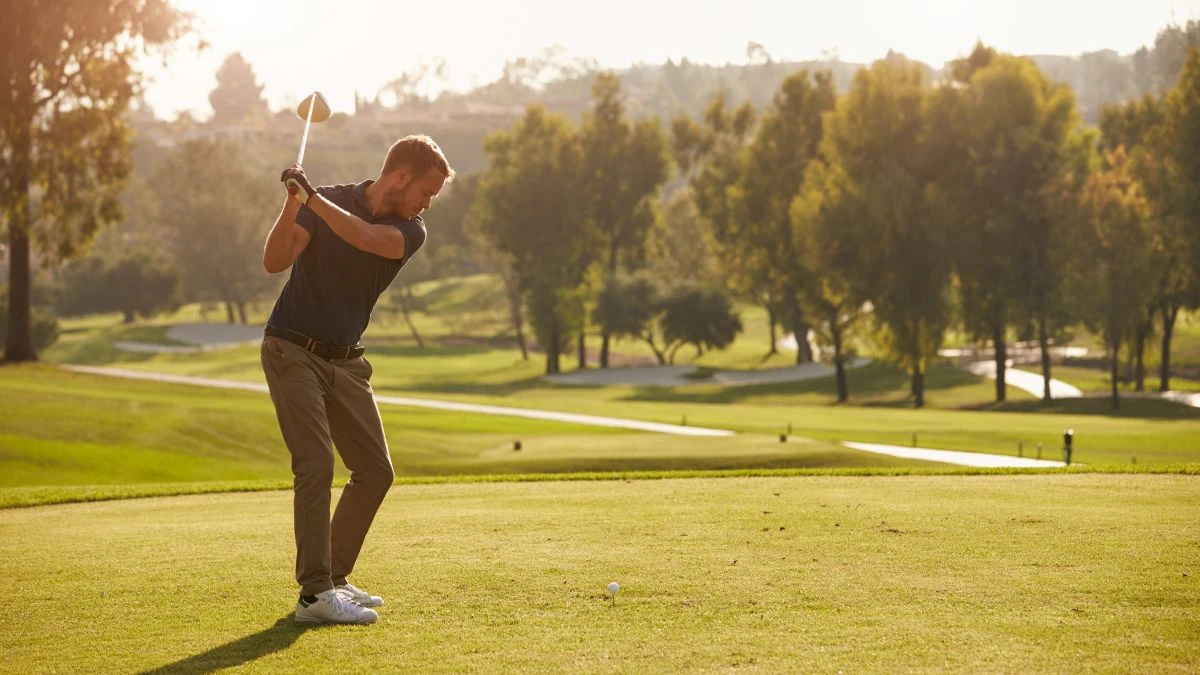
A $25,000 hole-in-one prize at a charity golf day might sound like an expensive gamble for the organisers. But when one lucky golfer landed the winning shot, the prize was paid through an insurance policy arranged specifically for the event.
For Aweso Insurance Managing Director Grant Mason, it’s one of his favourite examples of just how unusual the insurance industry can be.
“We arranged insurance for a charity golf day where there was a $25,000 prize for a hole-in-one. Instead of the organisation putting $25,000 at risk, insurance was arranged for the prize.
“And someone actually got the hole-in-one.”
After 25 years in the industry, Grant has learnt that insurance can extend far beyond the buildings, vehicles and public liability policies most business owners are familiar with.
From events and festivals to valuable collectables, unusual property risks and specialist business activities, there are insurance markets covering an extraordinary range of circumstances.
And for Grant, finding solutions to the more unusual requests is part of what makes his job interesting.
“One of the things I enjoy most about being a broker is when somebody comes to us with something unusual and says, ‘Nobody seems to know how to insure this.’”
But behind the unusual requests is a much broader lesson for businesses across the City of Moreton Bay.
Grant says many owners know they need insurance but don’t necessarily understand what a broker does, or the financial risks they might be overlooking.
Rather than starting with a particular policy, he believes the conversation should begin with understanding the business itself, from how it operates and makes money to the equipment it relies on, the people it employs and what could prevent it from operating.
That information helps a broker identify potential exposures, approach different insurers and explain the differences between available policies.
While online insurance platforms can be convenient for straightforward businesses, Grant says the challenge arises when owners don’t know which questions they should be asking.
“Two policies can both say ‘Business Insurance’ on the front and still provide very different protection.”
For more on underinsurance, rising replacement costs and the risks of outdated policies, read our earlier article, Why insurance gaps are catching businesses off guard.
One example is management liability, which can provide protection against certain claims involving directors, employment practices and regulatory matters, depending on the policy.
It’s an area Grant believes deserves more attention as businesses grow and take on employees.
He also encourages owners to ask how their broker is paid, whether through insurer commissions, broker fees or a combination of both, and to understand the ongoing service they’re receiving.
Because when something goes wrong, Grant says the relationship should extend well beyond arranging the original policy.
“Our job isn’t just to sell you the insurance you ask for. It’s to help you identify the risks you didn’t know you needed to ask about.”
And sometimes, that risk is a golfer making the perfect shot.